Where capital can be secondary to positioning, information asymmetry, and structural awareness.
The Daily Grind vs. The Wealth Equation
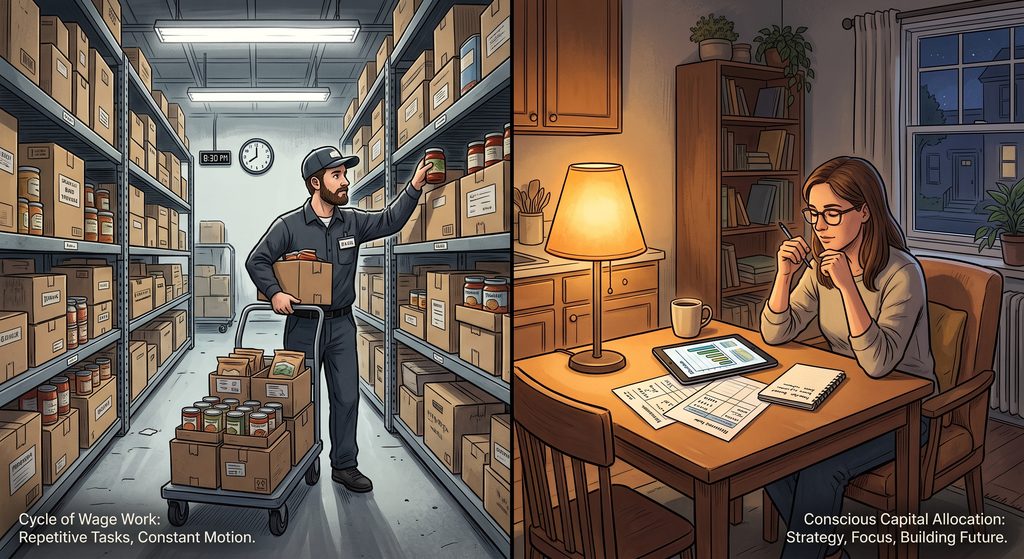
Consider two everyday workers:
- Maya, 35, splits her week between 24 hours at a regional retail warehouse and two weekend shifts as a certified nursing assistant. She is a single parent, managing a household on roughly $44,000 a year after taxes. Her life is scheduled down to the minute, and every dollar has a job before it even hits her checking account.
- David, 29, works an administrative desk job at a municipal logistics company, bringing home $52,000 annually. He lives with a roommate, pays off an auto loan, and puts whatever remains at the end of the month into a standard checking account that pays an interest rate of 0.05%.
The standard financial narrative tells Maya and David the same tired story: cut out small luxuries, save 10% of their paycheck, and wait forty years while an index fund slowly compounds.
That advice ignores a fundamental reality: when your starting margin is thin, saving alone is not enough to outpace structural inflation.
The common misconception is that wealth creation requires existing wealth—that only those with massive initial capital can participate in market upside. While large balance sheets generate effortless passive yield, history proves an entirely different driver for the working class: the information premium.
Wealth is built by regular wage earners when asymmetric knowledge and advance positioning replace raw capital.
Three Historical Wage Earners Who Leveraged Knowledge Over Capital
The following accounts illustrate how ordinary wage earners built substantial financial security not through lucky windfalls or inheritance, but by recognizing economic and regulatory shifts early.
1. The Janitor Who Mastered Dividend Arbitrage: Ronald Read
Ronald Read worked for decades as an automotive mechanic and a department store janitor. He never earned an executive salary. Yet, by the end of his life, he had built a multi-million-dollar estate.
- The Knowledge Trigger: Read ignored flashy speculative trends and studied the mechanics of dividend reinvestment and corporate longevity. He recognized a simple regulatory and market pattern: companies producing everyday necessities (utilities, infrastructure, consumer staples) consistently survived recessions and increased shareholder dividends year after year.
- The Execution: Instead of waiting for large sums to invest, he used fractional capital to buy shares in stable dividend-paying companies, automatically reinvesting every payout. He understood the mathematical power of uninterrupted compounding and tax-efficient hold cycles before the internet made that information ubiquitous.
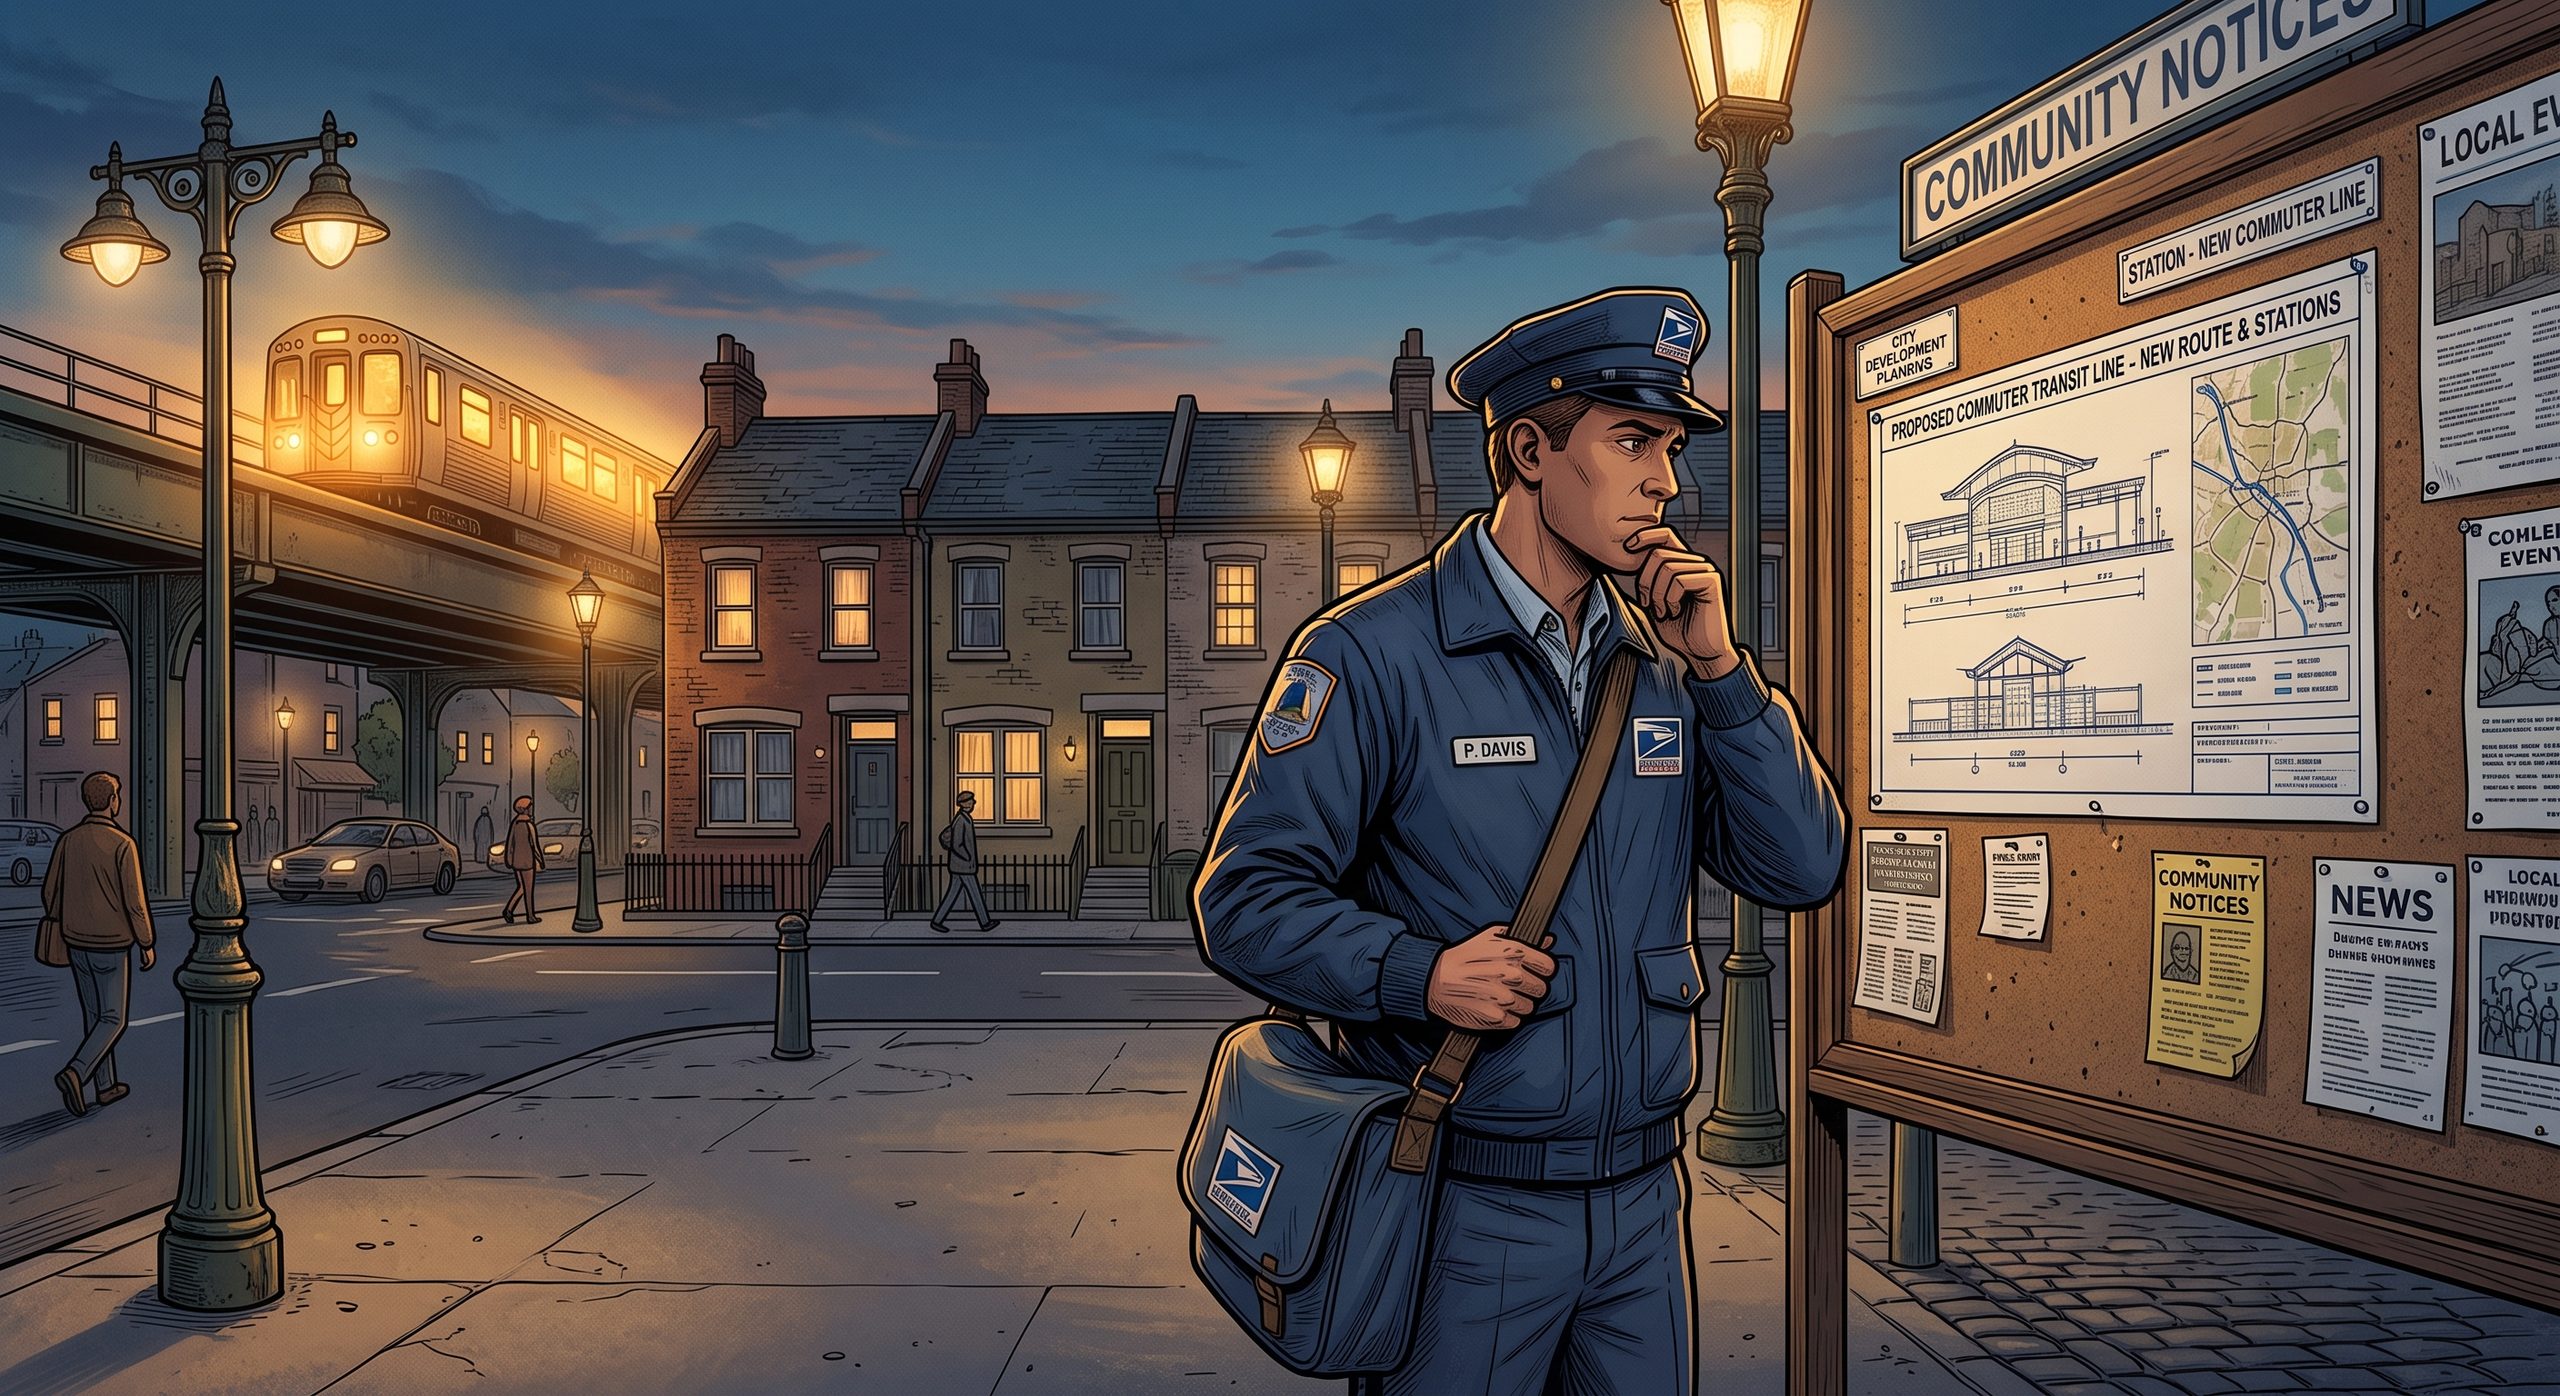
2. The Post Office Clerk and the Real Estate Rezoning Shift: Clara H.
During the mid-1970s, Clara, a postal distribution clerk in a mid-tier industrial town, noticed a pattern in local municipal filings and transport planning boards.
- The Knowledge Trigger: She learned that a planned interstate connector and commuter rail line would link her low-cost, working-class neighborhood directly to an expanding metropolitan medical hub within seven years.
- The Execution: Rather than moving away or waiting for institutional developers to buy up the neighborhood, she used a basic Federal Housing Administration (FHA) loan with minimal down payment to secure a modest duplex. She lived in one unit, rented the other to cover her debt service, and held on. When the transit hub opened, land values tripled. Clara’s edge was not a high net worth—it was simply reading publicly available municipal development reports before private developers moved in.
3. The Factory Floor Tech and the Supply Chain Bottleneck: Marcus T.
In the aftermath of the 2020 global supply chain shocks, Marcus, an hourly assembly-line technician, saw firsthand how semiconductor and component shortages paralysed automobile manufacturing.
- The Knowledge Trigger: While mainstream financial commentators were debating whether inflation was temporary, Marcus saw the reality on the ground: raw manufacturing materials, rare earth suppliers, and freight carriers were accumulating historic pricing power.
- The Execution: With modest savings, Marcus chose not to bet on high-risk tech stocks. Instead, he systematically reallocated his modest monthly contributions into beaten-down commodity logistics providers and raw-material exchange-traded funds (ETFs). By the time Wall Street institutional desks recognized the multi-year cycle of commodity inflation, Marcus had protected his purchasing power and captured significant capital growth, using direct industry insight that remote analysts overlooked.
The Structural Blueprint: Turning Low Capital into Compounding Advantage
| Strategic Lever | The Outdated Approach (Capital-Heavy) | The Knowledge-Driven Approach (Accessible to Wage Earners) |
| Cash Management | Leaving emergency funds in traditional bank checking accounts earning under 0.1%. | Deploying idle reserves into high-yield accounts, short-term Treasury bills, or fully backed digital assets to beat baseline inflation. |
| Market Entry | Waiting to save a large sum (e.g., $10,000) before opening brokerage or investment accounts. | Utilizing zero-commission fractional investing and automated dollar-cost averaging into defensive, broad-market index vehicles. |
| Information Gathering | Relying on mainstream financial news headlines after market moves have already occurred. | Monitoring regulatory shifts, local economic development plans, and macro supply bottlenecks directly. |
| Risk Management | Reacting emotionally to market sell-offs by liquidating assets into depreciating fiat. | Maintaining a defensive allocation model that balances liquid reserves with tangible, inflation-resistant assets. |
Three Practical Ways an Everyday Earner Can Position Early Today
Building wealth from an average wage requires executing small, deliberate steps based on structural awareness:
- 1. Eliminate the “Cash Drag” on Emergency Reserves: Holding hard-earned savings in a standard commercial checking account guarantees a loss of purchasing power over time. Auditing account yields and shifting liquid cash to competitive short-duration vehicles ensures capital works around the clock without incurring market risk.
- 2. Leverage Local and Industry Information Asymmetries: Every wage earner possesses specialized insight into their immediate work environment. Healthcare workers see medical supply trends; retail logistics workers see inventory build-ups or freight slowdowns; municipal workers see infrastructure zoning changes. Paying close attention to where operational money is flowing provides earlier, clearer signals than cable financial commentary.
- 3. Build High-Utility, Low-Cost Knowledge Stacks: Modern computational tools, automated research platforms, and open data sources make institutional-grade analysis accessible to anyone with an internet connection. Understanding how global interest rates, currency fluctuations, and energy bottlenecks impact everyday consumer prices allows you to adjust household spending and savings allocations well before price increases hit the register.
The Realistic Verdict
Can an average wage earner become wealthy? Yes. But not by copying institutional hedge-fund strategies, and not by leaving unmanaged cash to erode against macro inflation.
Wealth creation on an everyday income comes from early positioning driven by unvarnished information. When you understand how economic systems operate, where infrastructure is expanding, and how money maintains its value, small amounts of capital can achieve outsized, life-changing momentum.
Leave a Reply